For agency owners, managers and CSRs
The 90-60-30 renewal checklist for independent agencies.
Most agencies don't lose renewals at 15 days out. They lose them at 90, when nobody looked.
By the time a renewal shows up as urgent, the options have shrunk. There's no time to re-market properly, the client has already seen the carrier's notice, and the CSR is making a defensive phone call instead of a planned one.
The fix is a simple rhythm with three checkpoints, each with a clear job. It works for personal and commercial lines. The printable version is at the bottom of this page, so you can tape it next to every CSR's monitor.
90 days out
Review: know what's coming.
The goal at 90 days is to know what's coming, not to act on it yet.
- Pull the list. Every policy renewing in the 90-day window, personal and commercial, with an owner assigned to each one.
- Check the file for changes. New drivers, new vehicles, a home renovation, a new location, revenue or payroll changes on a commercial account. Clients rarely call to tell you, so ask.
- Flag the at-risk accounts. A prior-year increase, a recent claim, a client who complained about service, a household with only one line with you.
- Spot the gaps. A homeowners client with no umbrella, or a business owner with no personal lines with you. Renewal is the most natural time to ask.
- Set the date for the 60-day checkpoint. If it isn't on a calendar, it won't happen.
60 days out
Requote checkpoint: decide.
At 60 days you usually have a renewal premium or a good indication of one. This is the decision point.
- Compare the renewal to the current premium in dollars and percent. Anything that's gone up meaningfully, or any at-risk account from the 90-day review, gets a decision: re-market or hold.
- Re-market now, not at 20 days. Carriers need time, and so does the client.
- Make the increase call for anything that's gone up. Our renewal-increase call script walks through it: number first, then the reasons from the file, then the options.
- Request what's missing: updated values, a wind mitigation or roof inspection, loss runs, a signed application. Every document you're waiting on at 60 days is a fire drill at 10.
30 days out
Final check: no surprises.
- Confirm the decision for every policy: renew as-is, renew with changes, or move.
- Get signatures and documents back. Send anything that needs a signature now, and follow up within two business days.
- Confirm billing. Payment method, mortgagee or lienholder billing, and premium finance where it applies.
- Send a short written confirmation to the client: what's renewing, at what premium, and what changed. It's the email they'll look for in a year.
- Log the outcome. Renewed, renewed with changes, re-marketed and moved, or lost (and why). Six months of "why" tells you more about your book than any report.
Why the rhythm breaks down
It isn't that people don't care.
Every agency owner reading this already knows renewals need attention at 90, 60 and 30 days. The rhythm breaks because the renewal list lives in a spreadsheet or a report someone runs "when they get a chance," the client file lives somewhere else, and the email thread lives in someone's inbox. Each checkpoint means reassembling the picture from scratch.
That's why we built renewals into OneagencyOS around these same checkpoints. Each policy moves through a 90-day renewal review, a 60-day requote checkpoint and a 30-day final renewal alert, and the agency can set the day counts to match how it works. When a renewal reaches the 60-day checkpoint with an increase of 10% or more, OneagencyOS creates a high-priority carrier-review task for it, so the re-market decision doesn't depend on someone remembering. Renewals, the client record, quoting, documents, e-signatures and client communication all live in one system.
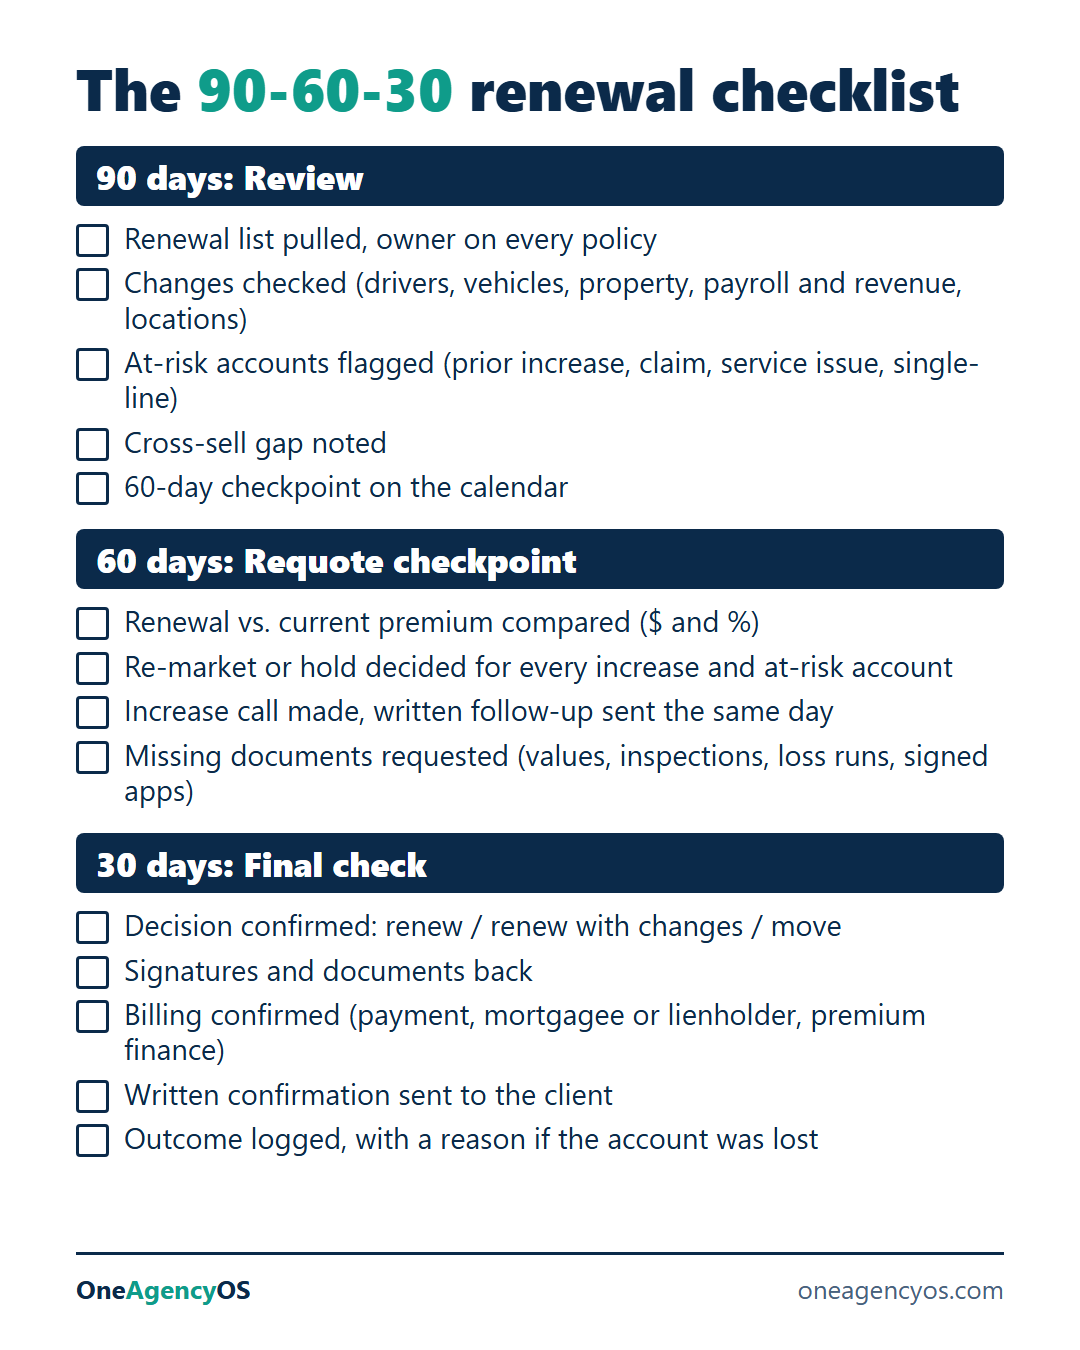
90 days: Review
- Renewal list pulled, owner on every policy
- Changes checked (drivers, vehicles, property, payroll and revenue, locations)
- At-risk accounts flagged (prior increase, claim, service issue, single-line)
- Cross-sell gap noted
- 60-day checkpoint on the calendar
60 days: Requote checkpoint
- Renewal vs. current premium compared ($ and %)
- Re-market or hold decided for every increase and at-risk account
- Increase call made, written follow-up sent the same day
- Missing documents requested (values, inspections, loss runs, signed apps)
30 days: Final check
- Decision confirmed: renew / renew with changes / move
- Signatures and documents back
- Billing confirmed (payment, mortgagee or lienholder, premium finance)
- Written confirmation sent to the client
- Outcome logged, with a reason if the account was lost
See your renewal list with the checkpoints built in.
Tell us about your agency and we will walk you through it.